Episode 23 | Right-of-Way Report Podcast
If you missed Episode 23 of the Right-of-Way Report Podcast on August 3, 2026, we talked about the July 30th decision of the Council for Bond Oversight. Here are the receipts.
We believe the Council for Bond Oversight (COBO) violated state law…possibly in more than one way… during their July 30th monthly board meeting when they conditionally approved the sale of up to $1.9 BILLION dollars in new revenue bonds for the Oklahoma Turnpike Authority (OTA) ACCESS program and $1 billion in refunding bonds to refinance existing debt.
The first potential violation involves Oklahoma Title 90, Section 10-3-4(a)(3)(I), which states that the State Bond Advisor is required to review the following documents prior to final approval, including a “(I) Letter from issuer’s attorney or bond counsel stating that there is no litigation pending or threatened relating to outstanding or proposed obligations or the issuer’s authority to enter into any agreements necessary to complete the proposed transaction.”
The regulation is unequivocal. It does not distinguish between material and immaterial litigation, nor does it limit the requirement to litigation challenging the validity of the bonds themselves.
The OTA has been under threatened litigation since January 23, 2026, when a Notice of Intent to Sue was served regarding the proposed East-West Connector project. That threatened litigation became pending litigation when Case No. 5:26-cv-01526-D was filed in the United States District Court for the Western District of Oklahoma on June 23, 2026. A Motion for Preliminary Injunction seeking to halt the project was subsequently filed on July 14, 2026.
Because litigation relating to the proposed project and the associated financing is both threatened and pending, the OTA could not truthfully provide the letter required by OAC 90:10-3-4(a)(3)(I). Without compliance with this mandatory regulatory prerequisite, the application for final approval is deficient.
PIKE OFF OTA told COBO all of this and more in our objections in June and again in July.
But the State Bond Advisor read the law differently, with the help of the OTA’s counsel, Eric Lair.
Around minute 4:30 in the video that a member of PIKE OFF OTA had to take because COBO was not recording it, she said that
“OTA has represented that the expenditures of bond proceeds will be directed across ACCESS Program projects, and the modularity of the program allows for that to happen.”
I have more to say about the legality of the “modularity” of their program, but hold on.
She goes on to say that
“In the event that certain construction equipment is not available, the funds can be deployed, the bond proceeds can be deployed, to other projects as is necessary. That is what is happening right now across the ACCESS program.”
You see where this is going, right?
She continues,
“As council is aware, litigation has been filed in federal court challenging certain federal permitting decisions related to the East-West Connector. As of today, OTA continues to hold permits for that project and is proceeding with construction under those permits.”
And whether those permits themselves withstand judicial scrutiny is precisely one of the issues now before the federal court.
Just look at the video of their bridge construction impacting the South Canadian River AND the delineated wetlands.
Not to mention the raw sewage spewing in from the City of Moore.
Moving on…. (minute 6:00 in the video)
“However, should a court issue an order prohibiting further construction on the East-West Connector, or grant any requested injunctive relief, as outlined in the motion, OTA will be forced to comply. Should a court dismiss certain requests for relief that allow for the issuance of bonds by OTA, while granting relief in other matters related to the East-West Connector, the programmatic nature of the bond issue and of this application would simply result in expenditure of bond proceeds on other projects across the ACCESS Program.”
She finishes the discussion about the litigation by stating…..
“I will note that the current litigation does not challenge OTA’s statutory authority to issue revenue bonds for the ACCESS Oklahoma Program. That authority was upheld and that determination was made by the Oklahoma Supreme Court back in the validation proceedings that culminated in 2023.”
Please see my discussion on the contentious Oklahoma State Supreme Court split decision for both the East-West Connector and the Southern Extension.
And if there were any question about whether COBO understood the significance of the federal litigation, just look at the conditions they placed on the bond approval.
COBO’s 12 Conditions for the Bond Sale
Since COBO would not give us the packet of information, a member of the press let us take a picture of the recommended conditions. We have since Open Record Requested (ORR) the packet, but we have been ghosted. Again.
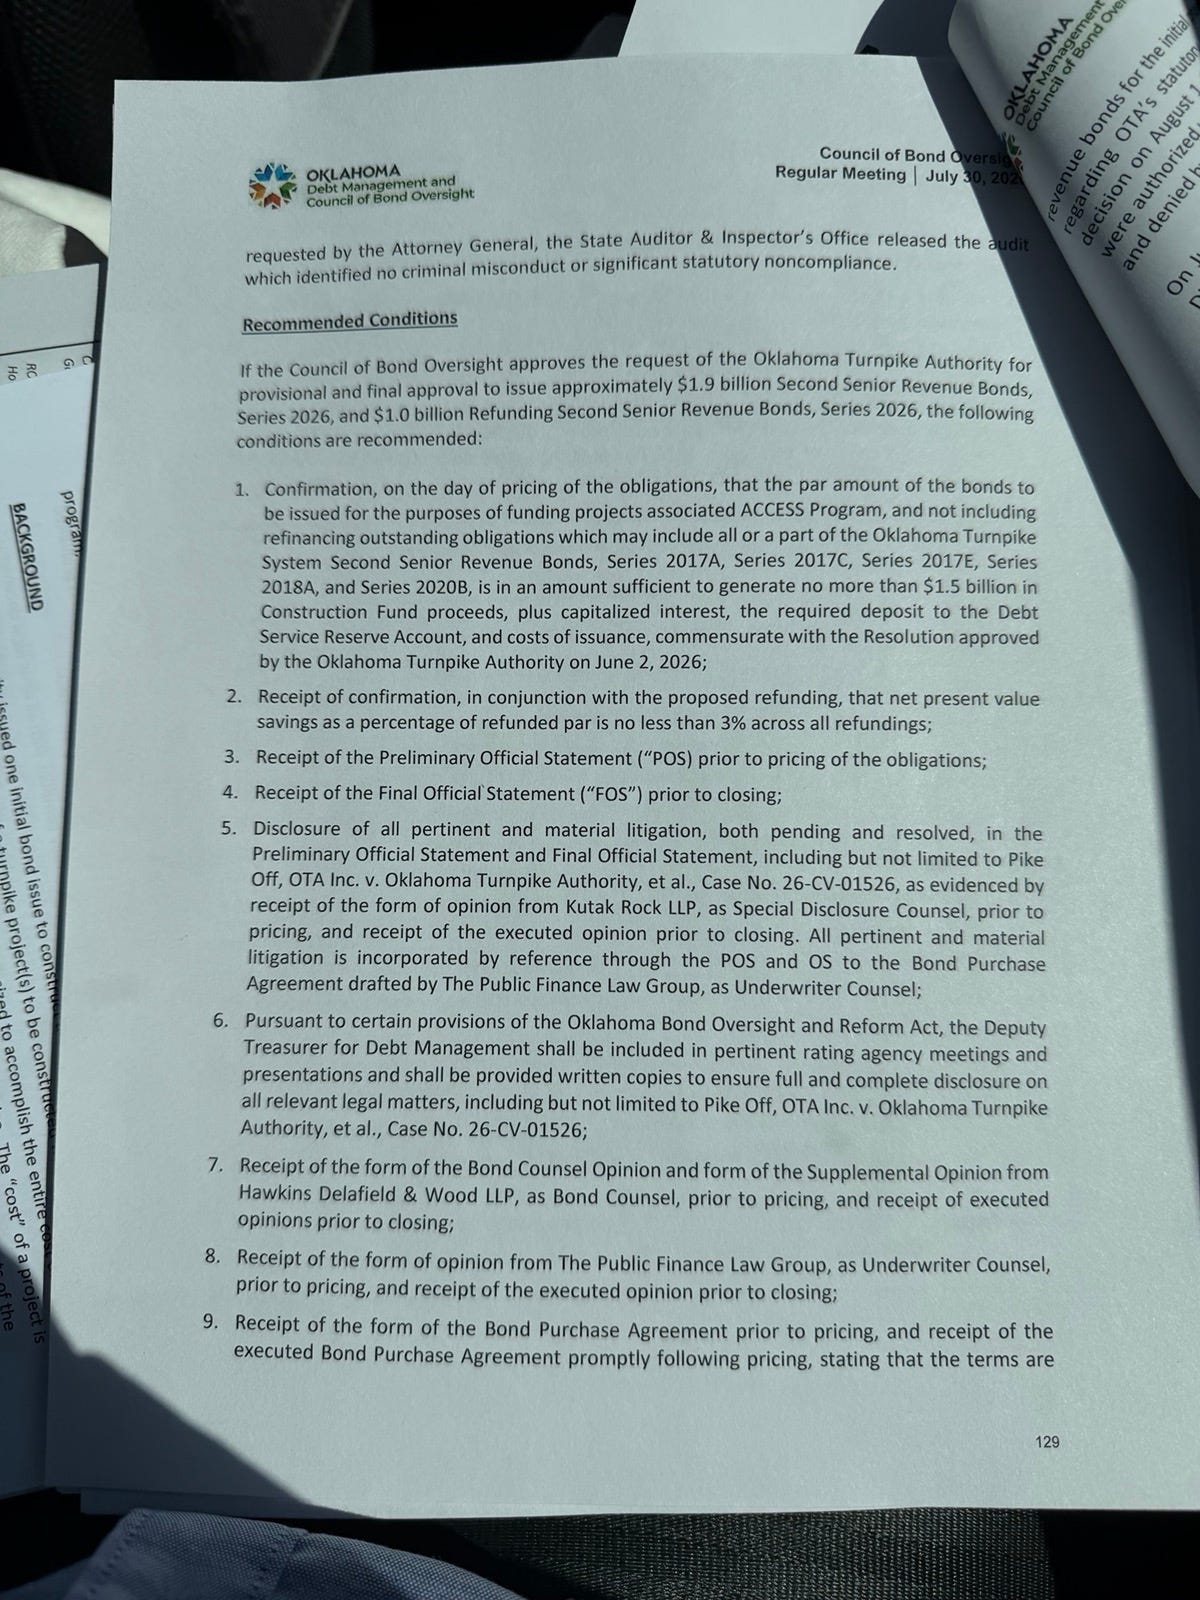
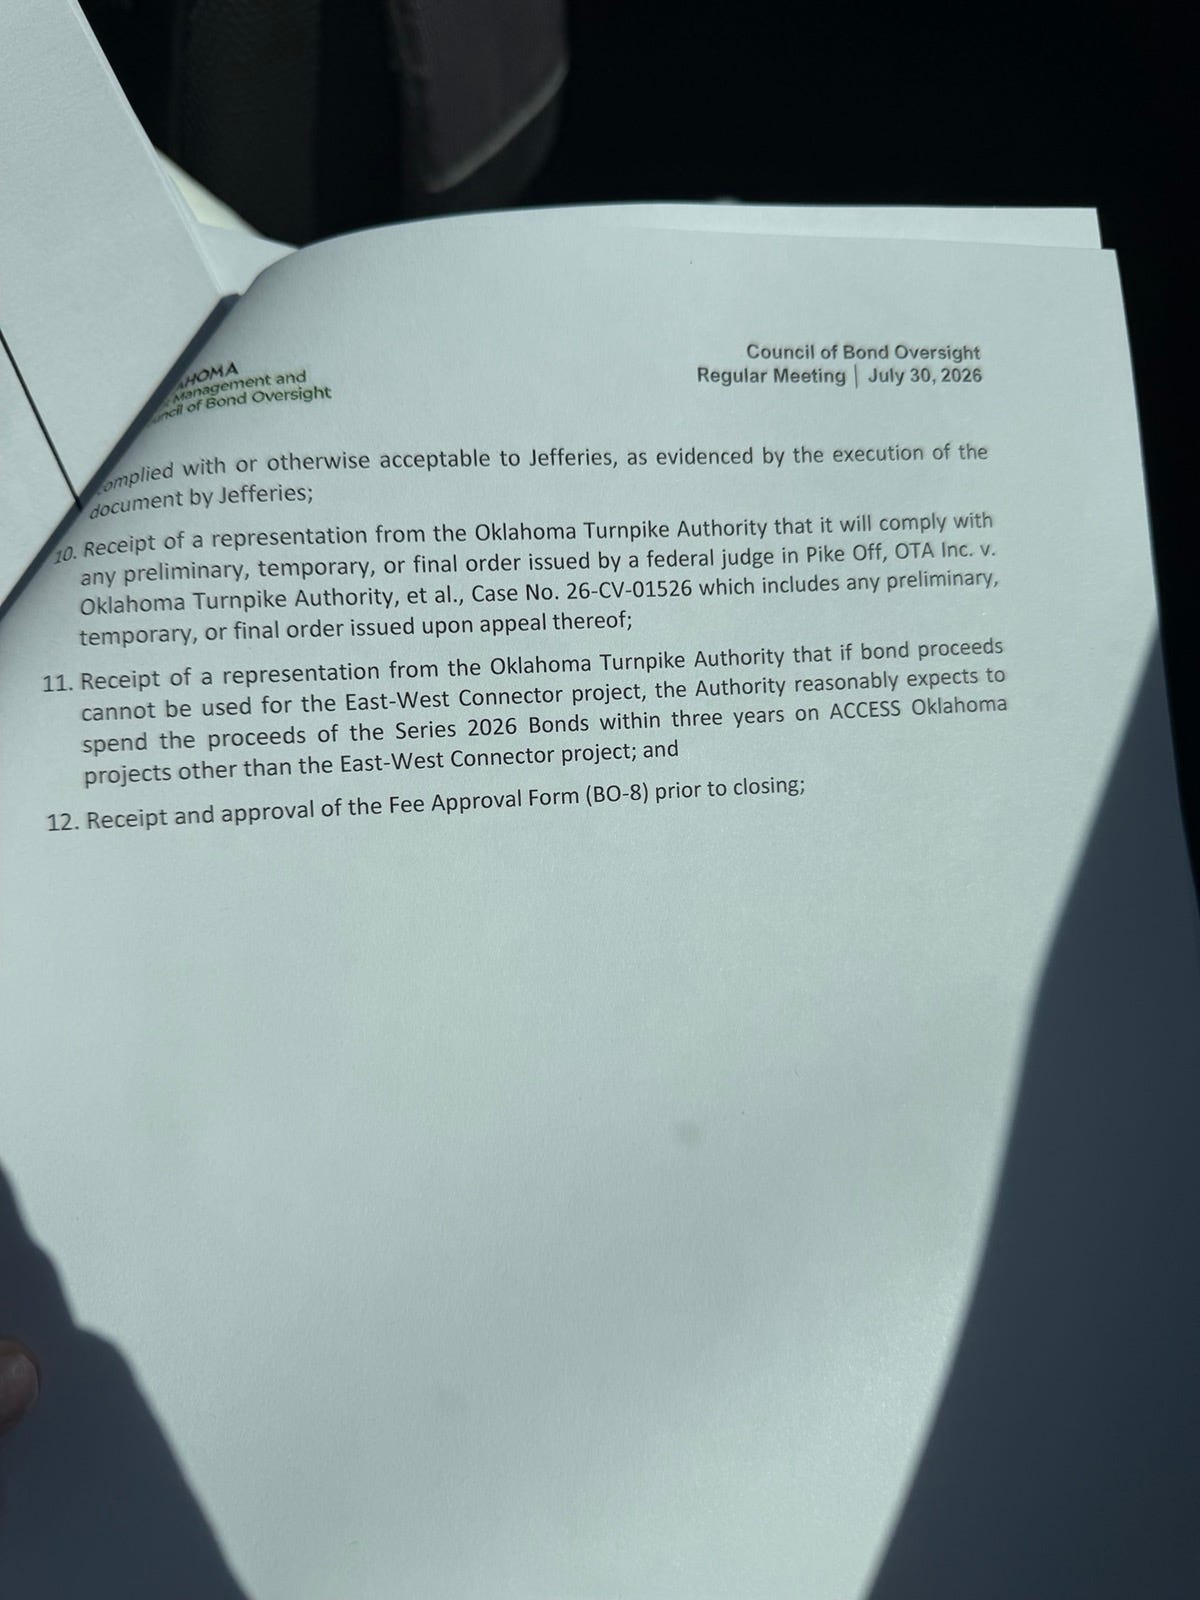
So What Were COBO’s 12 “Conditions”?
COBO didn’t give OTA unconditional green light. Instead, it attached 12 conditions to the proposed $1.9 billion in new ACCESS bonds and $1 billion in refunding bonds.
That sounds reassuring.
Until you read them.
Some are legitimate financial safeguards. Others essentially amount to “give us another letter saying everything is okay.” And several rely upon representations or legal opinions coming from OTA itself or professionals being paid as part of the bond transaction.
Here’s what the 12 conditions actually mean in plain English:
Don’t raise more than $1.5 billion for ACCESS construction.
OTA can issue approximately $1.9 billion in new bonds, but the amount actually deposited into the Construction Fund for ACCESS projects cannot exceed $1.5 billion, plus the other permitted amounts such as capitalized interest, reserves and issuance costs.Translation: COBO is putting a ceiling on how much new construction money OTA can actually generate from this particular bond sale.
The refinancing has to save money.
For the $1 billion refunding portion, OTA must demonstrate net-present-value savings of at least 3% of the refunded principal.Translation: Don’t refinance old bonds just for the sake of refinancing them. The transaction has to produce a minimum level of financial savings.
Provide the Preliminary Official Statement before the bonds are priced.
The POS is essentially the preliminary disclosure document given to potential investors describing OTA, the bonds, financial information, risks, litigation and other material information.Translation: COBO wants to see the investor disclosure document before the interest rates and price are finalized.
But: Receiving a document is not the same thing as independently verifying everything in it.
Provide the Final Official Statement before closing.
After pricing, OTA must provide the final version of the disclosure document before the transaction closes.Translation: Give COBO the final paperwork before the money changes hands.
Again: receipt ≠ independent verification.
Tell investors about the lawsuit.
OTA must disclose all “pertinent and material litigation,” specifically including PIKE OFF OTA v. OTA, in both the preliminary and final Official Statements. Kutak Rock, acting as Special Disclosure Counsel, must provide an opinion concerning those disclosures.Translation: The federal lawsuit isn’t stopping the bond sale. Instead, COBO is requiring OTA to tell the investors about it and obtain a legal opinion from the disclosure lawyer. COBO appears to be addressing the securities-disclosure consequences of litigation that everyone acknowledges exists.
Let the Deputy Treasurer sit in on the rating-agency meetings.
The Deputy Treasurer for Debt Management must be included in relevant rating-agency meetings and presentations and receive written copies concerning legal matters, specifically including the PIKE OFF OTA litigation.Translation: Someone from the State Treasurer’s office gets a seat at the table when OTA talks to the rating agencies about these bonds.
That’s more oversight. But again, observing what OTA tells rating agencies isn’t necessarily independently determining whether OTA is legally compliant.
Get an opinion from Bond Counsel.
Hawkins Delafield & Wood LLP, OTA’s Bond Counsel, must provide its proposed legal opinion before pricing and the executed opinions before closing.Translation: Get a lawyer’s letter saying the bond transaction satisfies the matters covered by that lawyer’s opinion.
Stop and think about that for a minute. Who’s checking the checkers?
A legal opinion is important in municipal finance, but it is not the same as COBO independently investigating every factual predicate underlying that opinion.
Get another opinion—from the underwriter’s lawyer.
The Public Finance Law Group, acting as counsel to the underwriter, must provide its form of opinion before pricing and its executed opinion before closing.Translation: Get another lawyer’s letter.
This lawyer represents the underwriter’s interests in the transaction. Again, that’s a normal transactional protection,but it shouldn’t be confused with independent governmental investigation of OTA’s statutory and Trust Agreement compliance.
Give COBO the Bond Purchase Agreement and make sure Jefferies accepts it.
COBO must receive the proposed Bond Purchase Agreement before pricing and the executed agreement after pricing. Its terms must comply with, or otherwise be acceptable to, Jefferies, the underwriter, as evidenced by Jefferies executing it.Translation: The company buying/underwriting the bonds has to agree to the contract governing its purchase.
This may be normal bond-closing mechanics, but as an “oversight condition,” it’s hardly earth-shattering. Jefferies signing an agreement acceptable to Jefferies primarily tells you that Jefferies agreed to the deal.
OTA must promise to obey the federal judge.
OTA must provide a representation that it will comply with any preliminary, temporary or final order entered by the federal court in the PIKE OFF OTA litigation—including orders entered on appeal.
Translation: OTA must promise COBO that it will obey a federal court order.
A governmental entity doesn’t get to decide whether to obey a federal judge. If the court enters a binding order against OTA, OTA is already legally required to comply with it.
So the obvious question is: What additional protection does a written promise to obey a court order actually provide?
If the court stops the East-West Connector, OTA promises it can spend the money somewhere else.
OTA must represent that if the bond proceeds cannot be used for the East-West Connector, it “reasonably expects” to spend the Series 2026 proceeds on other ACCESS projects within three years.
Translation: If PIKE OFF OTA wins an injunction affecting the East-West Connector, OTA says: Don’t worry—we have somewhere else to spend the money.
This is potentially one of the most consequential conditions because it embodies the State Bond Advisor’s “modularity” argument.
But it also raises the question from our Trust Agreement objection: Are those other projects independently eligible to receive these second-senior bond proceeds?
A representation that OTA expects to spend the money elsewhere doesn’t itself establish that the alternate expenditure complies with every applicable statute and provision of the Trust Agreement.
Submit the Fee Approval Form before closing.
COBO must receive and approve the BO-8 Fee Approval Form.
Translation: Show COBO who is getting paid and how much before the deal closes.
That’s useful transparency—but it doesn’t resolve the substantive legal objections to the issuance itself.
The Bigger Problem
Read together, these conditions reveal something important about what COBO did on July 30.
COBO did not resolve any of the substantive objections we raised about whether OTA was already complying with Oklahoma law and its 1989 Trust Agreement.
Instead, many of its conditions concern what must happen later—before pricing or closing.
Send us the Preliminary Official Statement.
Send us the Final Official Statement.
Get an opinion from Special Disclosure Counsel.
Get an opinion from Bond Counsel.
Get an opinion from Underwriter Counsel.
Have OTA represent that it will obey the federal court.
Have OTA represent that it can spend the money somewhere else if the East-West Connector is stopped.
But who independently determines whether the underlying representations are actually true?
Who independently determines whether the alternate ACCESS projects are eligible for these bond proceeds under the Trust Agreement?
Who verifies that the required project-level financial tests have actually been performed?
Who reconciles the missing completion dates and financial projections identified in our objection?
Who determines whether OTA can truthfully certify that it is not in default under its Trust Agreement?
And perhaps most importantly:
Who at COBO independently determined that OTA was already in compliance with Oklahoma law before voting to authorize another $2.9 BILLION transaction?
Conditions 1 and 2 are genuine financial constraints; 3, 4, 9 and 12 are largely transaction/document-closing requirements; 5–8 involve disclosure and professional legal opinions; and 10–11 are the extraordinary litigation-related conditions created specifically because COBO knew the federal lawsuit existed.
COBO knew litigation existed—so much so that it created multiple special conditions specifically addressing that litigation while simultaneously allowing a transaction to proceed under a regulatory framework that we argue requires a letter stating there is no pending or threatened litigation.
But the litigation wasn't the only problem COBO had in front of it.
COBO Had Another Problem: OTA’s Own Bond Documents
There was another elephant in the room on July 30.
Even if COBO somehow convinced itself that pending federal litigation wasn’t enough to stop this bond application, PIKE OFF OTA had provided COBO with another detailed objection identifying something much bigger:
Evidence that OTA may not be complying with Oklahoma statutes OR the very Trust Agreement that governs its ability to issue these bonds.
That matters because OTA’s 1989 Trust Agreement isn’t some dusty historical document sitting in a filing cabinet.
It is essentially the rulebook governing the relationship between OTA and its bondholders.
It establishes conditions OTA has agreed to satisfy before additional debt can be issued. Those conditions are designed to protect the financial integrity of the Turnpike System and the people investing billions of dollars in it.
Our objection identifies three alleged violations of Oklahoma statutes and nine areas of alleged noncompliance with that Trust Agreement.
(I talked about the OTA’s Trust Agreement and statutory violations in a previous substack as well).
Strip away the bond jargon and the problems are surprisingly easy to understand.
1. Did OTA actually prove these new turnpikes are financially feasible?
Oklahoma law requires the feasibility and economic soundness of Turnpike Projects and Improvements to be determined before revenue bonds are issued.
The ACCESS program is a conglomeration of many individual turnpike projects - and it isn’t the same program OTA announced in 2022 anymore. Projects have been added, removed or changed.
The Bixby toll bridge was added in 2026.
The Gilcrease Extension remains unresolved.
Our objection argues that requirement must be applied to the individual new turnpike projects—not simply ACCESS Oklahoma as one enormous program.
That’s important because you cannot meaningfully determine whether a project is economically sound if you don’t know exactly what you’re building, what it will cost, when it will open, how much traffic it will attract and how much revenue it will generate.
And the Trust Agreement goes even further.
For certain new turnpike projects, Section 715(a)(1) requires a financial test before second-senior bond proceeds can be used: projected revenues from that project must be sufficient to cover its operating expenses and required reserve-maintenance deposits after the first five years of service.
So this isn’t merely:
“Can the Turnpike System as a whole afford more debt?”
The objection argues there is also a project-level question:
“Is THIS new turnpike eligible to be built with THIS type of bond money?”
Because if the answer is no, calling ACCESS a “program” doesn't magically make the project eligible.
And according to the objection, approximately $4.9 billion of the $8.7 billion ACCESS program consists of projects subject to this eligibility requirement, which is about 56% of the program.
2. OTA’s “modularity” argument may actually expose the problem.
Remember what the State Bond Advisor told COBO?
If construction on one project is stopped, OTA can simply deploy the bond proceeds somewhere else in ACCESS.
That sounds reassuring until you read the Trust Agreement.
The objection argues that ACCESS cannot simply be treated as one giant, interchangeable bucket of projects. Certain new turnpikes must independently satisfy eligibility requirements before second-senior bond proceeds can be used for them. And the financing analysis depends upon when those projects are actually completed and how long the bonds financing them remain outstanding.
In other words:
“We’ll just spend the money somewhere else” may not answer the legal question at all.
Before moving bond proceeds to another project, shouldn’t someone first determine whether that project is legally and financially eligible to receive those particular bond proceeds?
That is exactly the type of question COBO should have been asking.
3. OTA appears to have changed what “Completion Date” means.
This may sound technical. It isn’t.
The Trust Agreement requires financial projections extending for years after a project is completed.
Why?
Because bondholders need to know what the Turnpike System looks like when the thing they’re financing is actually operating, not merely while it’s under construction.
Section 209(c), according to the objection, requires the Consulting Engineer to identify the individual projects, their costs, their estimated completion dates, and certify that bond proceeds plus other available funds will be sufficient to pay those costs.
But the objection says the 2023 and 2025 Consulting Engineer statements did not provide estimated completion dates for individual ACCESS projects and that the 2025 statement also failed to certify that the proceeds plus other funds would be sufficient to pay the projects’ costs.
Instead, OTA has treated ACCESS as a 15-year program.
That’s a huge distinction.
Finishing spending one round of bond money is not the same thing as finishing the individual turnpike that the money is supposed to build.
And if you move the definition of “completion,” you also move the period over which the required financial calculations are performed.
4. That leads directly to another problem: How far into the future did OTA actually run the numbers?
The Trust Agreement requires projected operating results after project completion. In plain English, this is basically a future cash-flow analysis: expected toll revenue, operating expenses, maintenance reserves, debt-related reserves and other financial obligations.
According to the objection, if the original ACCESS projects aren’t completed until 2036, the required analysis would need to extend at least through 2041; five complete bond years after completion. And the Gilcrease Extension doesn’t even have a defined completion date, making that calculation even more problematic.
Yet the objection says OTA’s financial projections for the 2023 bonds stopped at 2032, while projections for the 2025 bonds stopped at 2033.
That’s not a minor accounting detail.
If the Trust Agreement requires you to demonstrate financial performance for five years after the projects are completed, you can’t stop the spreadsheet years before the projects themselves are scheduled to be finished.
5. Then come the certifications.
This is where the rabbit hole gets even deeper.
The Trust Agreement doesn’t merely suggest that OTA perform these analyses.
Certain people are required to certify that requirements have been satisfied before the Trustee releases the bonds.
The objection identifies certifications from OTA’s executive directors in connection with the 2023 and 2025 bonds stating that OTA was not in default under the Trust Agreement.
And Section 209(g) requires OTA’s counsel to provide an opinion stating that the bonds were properly authorized and that all conditions precedent to delivery of the bonds have been fulfilled.
That creates an extraordinarily important question:
If the underlying requirements weren’t actually satisfied, how can the certifications saying OTA complied with them be accurate?
That’s the question COBO should have answered before approving another bond issue.
6. Then there is the Consulting Engineer itself.
There is one more issue raised in our objection that deserves a closer look: the independence of OTA’s Consulting Engineer.
Under the Trust Agreement, the Consulting Engineer has significant responsibilities related to evaluating projects, costs, completion dates, financial sufficiency and other matters that ultimately help protect the interests of bondholders.
OTA’s Consulting Engineer is Olsson.
But Olsson isn’t just evaluating and providing oversight of OTA’s system.
Olsson is also being paid by OTA to perform engineering and design work on ACCESS projects.
Our objection alleges that this dual role raises a conflict under Oklahoma law and, at a minimum, an obvious question about the independence of one of the professionals whose work is relied upon in the bond-financing process.
And this one deserves its own rabbit hole.
Who Is Watching the Watchdog?
Olsson occupies two very different positions within the Oklahoma Turnpike Authority’s financial and engineering structure.
On one hand, Olsson serves as OTA’s bond consulting engineer, a role that is supposed to represent the interests of the bondholders. In that capacity, Olsson conducts pavement condition evaluations and annual bridge inspections, helps establish OTA’s annual capital priority list, analyzes anticipated maintenance needs, recommends funding levels for maintenance and operations, attends bond meetings, and approves certain requisitions associated with bond-funded projects.
In other words, Olsson helps answer a very important question:
What work does the Oklahoma Turnpike Authority need to spend money on?
But Olsson also works on the other side of that equation.
The company is simultaneously a prime engineering vendor for ACCESS Oklahoma and performs engineering and design work on OTA capital projects.
Which raises an obvious question:
How independent can the company evaluating OTA’s infrastructure needs be when that same company can financially benefit from the engineering work generated by those evaluations?
I’m not suggesting that Olsson engineers are intentionally exaggerating pavement deterioration or recommending unnecessary bridge work. That’s not the point.
The problem is structural.
Imagine hiring someone to inspect your house and determine which repairs should receive priority and then allowing that same company to compete for millions of dollars in contracts to design those repairs.
Even if every recommendation is technically defensible, wouldn’t you want some separation between the person determining what needs to be fixed and the company that can make money designing the fix?
And this arrangement goes even further.
According to the State Auditor’s investigative audit, Olsson, in its role as consulting engineer, has review oversight over the work of OTA’s design engineers while simultaneously serving as one of the design and engineering consultants performing ACCESS work.
Read that again.
The firm providing independent engineering oversight can also be one of the firms whose engineering work exists within the very program it oversees.
Maybe there are internal firewalls, recusals, separate personnel, or contractual safeguards that adequately address those competing roles.
If so, show us.
Because when billions of dollars in bond proceeds are being authorized—and the consulting engineer is supposed to provide assurance to the people lending OTA that money—the public and the bondholders deserve to know exactly where independent oversight ends and paid engineering work begins.
And that brings us to another problem with COBO's July 30 decision—the public couldn't even see all of the information COBO was using to make it.
Was this really an Open Meeting?
Council members weren’t making this $2.9 BILLION decision in a vacuum.
They had meeting materials in front of them.
The State Bond Advisor repeatedly referenced those materials during the presentation. They contained the staff analysis, recommendations and, critically, the conditions being proposed for OTA’s bond approval.
But the public didn’t have them.
We asked for them.
We were refused.
And yet, according to what we subsequently learned, those same materials were provided to members of the press.
Think about what that means.
Members of a governmental body were conducting public business, deliberating over a request involving up to $2.9 billion in public-authority debt, while relying upon documents the citizens sitting in the room could not see.
Those documents weren’t incidental. They contained information directly relevant to the action COBO was being asked to take including the conditions under which OTA would be permitted to move forward with the bond transaction.
How exactly is the public supposed to meaningfully observe its government conducting business when the government is discussing documents that it refuses to let the public see?
And if those documents could be handed to members of the press, what possible justification existed for refusing to provide them to citizens who were physically present at the meeting and specifically asked for them?
That raises a serious question under Oklahoma’s Open Meetings Act.
The purpose of an open meeting isn’t simply to allow citizens to occupy chairs in the same room while government officials make decisions - even though the first two rows of chairs were RESERVED for “STAKEHOLDERS” that apparently didn’t include the public.
The meeting has to actually be open.
And that brings us to something PIKE OFF OTA knows far too well: the Oklahoma Open Meetings Act…and COBO’s apparent failure to understand what meaningful government transparency requires.
And Where Was the Attorney General’s Office?
There is one more person sitting at the COBO table who cannot be ignored.
Assistant Attorney General Jon Dutton.
Dutton isn’t simply an observer at these meetings. COBO’s own materials identify him as “Office of the Attorney General — Legal Counsel.” And Oklahoma law expressly provides that “The Attorney General shall provide legal counsel to the Council.”
That makes what happened on July 30 even harder to understand.
We didn’t walk into that meeting with a vague complaint that we didn’t like OTA’s bond issue. We provided COBO with the actual regulation requiring review of a letter stating that there is no pending or threatened litigation relating to the proposed obligations or the issuer’s authority to complete the transaction.
Everyone acknowledged that litigation existed.
In fact, COBO imposed multiple conditions specifically because that litigation exists.
So what legal advice did COBO receive from its Attorney General-appointed counsel before voting to conditionally approve this transaction?
Did counsel conclude that OAC 90:10-3-4(a)(3)(I) does not apply? If so, what is the legal basis for that interpretation?
Did counsel independently evaluate the alleged statutory and Trust Agreement violations presented to COBO? Did he advise the Council that those objections were legally insufficient? If so, why?
And when members of the public were denied access to the very materials COBO was using to conduct the meeting, what advice did the Council receive from its legal counsel about Oklahoma’s open-government laws?
These aren’t rhetorical technicalities.
The Attorney General describes itself as Oklahoma’s chief legal and law-enforcement office, responsible for advising state agencies and departments.
If the Council’s own attorney did not advise COBO to stop and resolve these legal questions before authorizing another multibillion-dollar transaction, the public deserves to know why.
And if he did raise those concerns and COBO proceeded anyway, the public deserves to know that too.
Either way, somebody needs to explain what happened at that table.
So Who Is Overseeing the Council for Bond Oversight?
OTA’s consultants provide analyses. OTA’s professionals provide certifications. OTA’s attorneys provide opinions. The underwriter’s attorney provides another opinion. Special Disclosure Counsel provides another. OTA provides representations. COBO receives the documents.
But somewhere in that chain, somebody has to stop collecting assurances and actually verify whether the underlying requirements have been satisfied.
That’s what oversight is supposed to mean.
We didn’t ask COBO to believe PIKE OFF OTA.
We gave them the statutes.
We gave them the Trust Agreement.
We gave them the pending federal lawsuit.
We gave them detailed written objections.
We asked them to investigate.
Instead, they approved the transaction with conditions.
And sitting at the table while all of this happened was legal counsel from the Oklahoma Attorney General’s Office.
So if OTA’s lawyers are checking OTA, COBO is checking OTA, and the Attorney General’s Office is advising COBO, who is independently checking whether any of them are actually following the law?
Just us?
We have raised the questions. We have provided the statutes, the Trust Agreement, the litigation and the documentation. But at some point, someone with the authority to enforce those requirements has to decide whether they were actually followed.
Ultimately, a court may have to answer the question COBO should have answered before approving another $2.9 billion in debt: Did OTA—and COBO itself—follow the law?